Japan has just taken another historic step away from the era of ultra-cheap money — but the market reaction delivered a warning that raising rates does not automatically solve a currency or inflation problem.
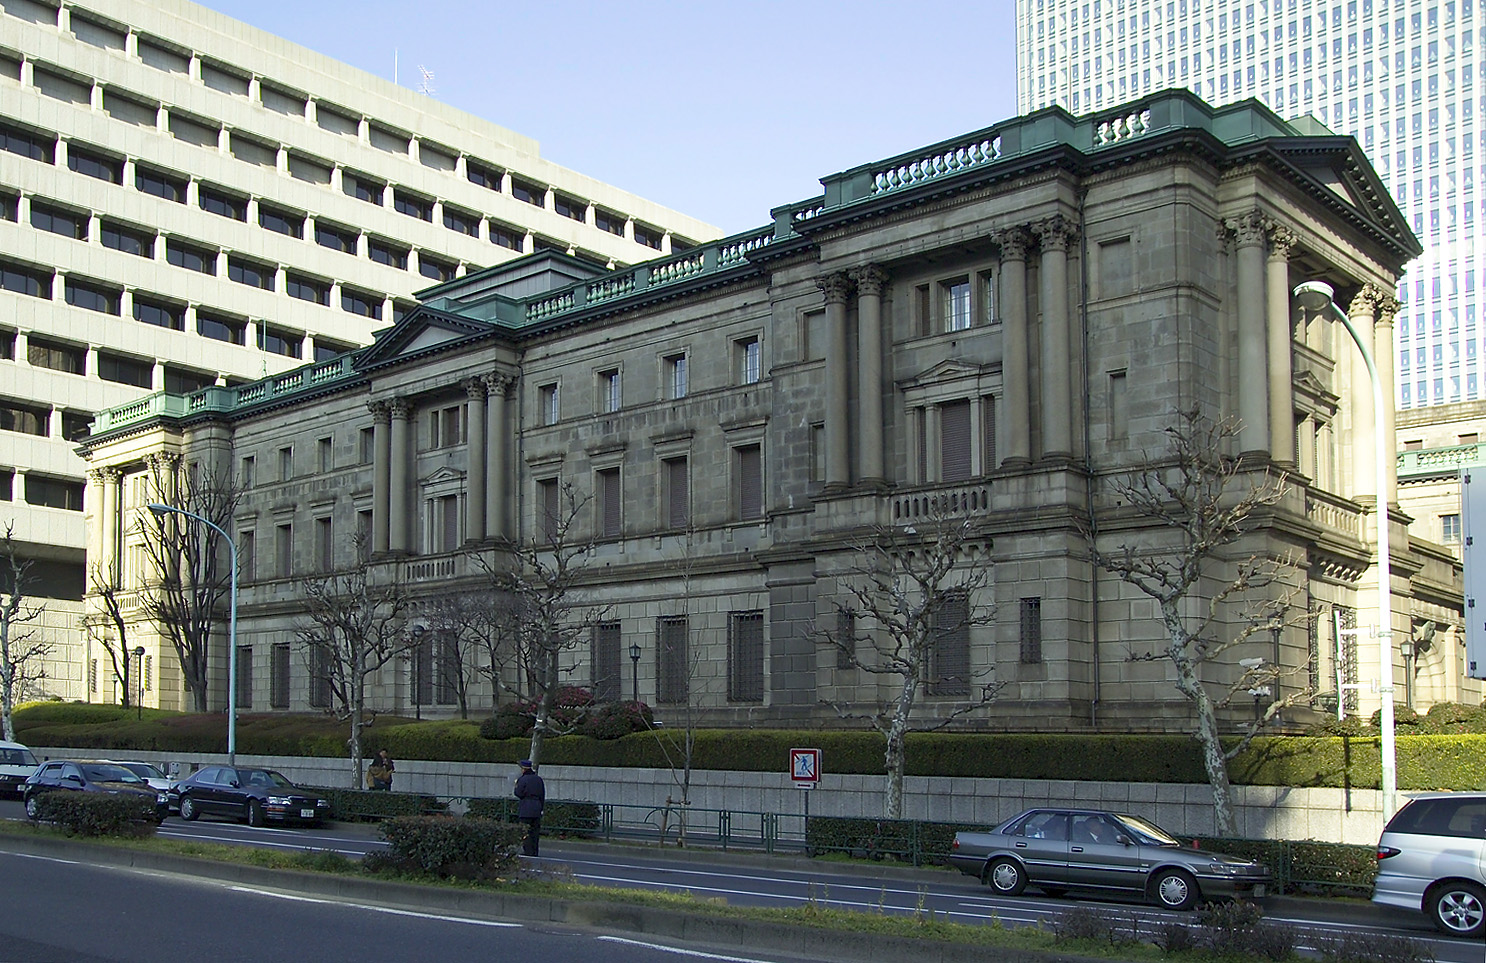
On Friday, September 18, the Bank of Japan raised its policy interest rate from 1% to 1.25%, its highest level in 31 years. The decision passed by a 7-2 vote and was aimed at limiting the risk that inflation moves above the central bank’s 2% target. Reuters reported that Governor Kazuo Ueda also signaled a new phase in which policymakers are prepared to act preemptively against inflation rather than waiting for it to become entrenched.
The surprise came afterward: the yen weakened instead of strengthening. That counterintuitive reaction helps explain why this is more than a Japan story. It is part of a broader global shift in which central banks are again confronting stubborn price pressures, high energy costs and difficult trade-offs between inflation and growth.
A historic rate move after decades of cheap money
For much of the past three decades, Japan was the global outlier. While other major economies moved through cycles of higher and lower interest rates, Japan spent years fighting deflation and weak demand with exceptionally loose monetary policy.
Friday’s move takes the benchmark rate to a level unseen since the mid-1990s. The Associated Press reported that the rate was lifted by a quarter percentage point, from 1% to 1.25%, as the BOJ continues normalizing policy after years of near-zero or negative rates.
The change matters directly to Japanese households and businesses. Higher policy rates can feed into borrowing costs, including some mortgages and corporate loans. They can also improve returns for savers over time. But the BOJ faces an unusually delicate balancing act: tighten too slowly and inflation may become harder to contain; tighten too aggressively and higher financing costs could weigh on an economy whose recovery remains fragile.
Why did the yen fall after a rate hike?
Normally, higher interest rates can make a currency more attractive because investors may earn better returns on assets denominated in that currency. Yet the yen fell to a two-week low after Friday’s decision.
Reuters reported that investors focused on the two dissenting votes and questioned how committed the BOJ would be to additional increases. The rate hike itself had also been widely expected, meaning much of the move was already reflected in market prices before the announcement.
There is another important factor: Japan’s rates remain substantially below U.S. rates. The Federal Reserve raised its target range to 3.75%-4.00% on September 16 and indicated that further tightening could follow. Reuters reported that the Fed’s quarter-point increase was accompanied by projections pointing toward more hikes in coming months.
As long as the gap between U.S. and Japanese interest rates remains wide, investors can still have an incentive to favor dollar-denominated assets over yen assets. Currency markets also trade on expectations: what policymakers are likely to do next can matter as much as what they did today.
The bigger story: the world’s central banks are fighting inflation again
The BOJ decision arrives during a renewed global inflation debate. Higher energy prices have complicated the outlook, while central banks must decide how much of an energy-driven price shock should be countered with higher borrowing costs.
That tension is already visible in global investment flows. Data reported by Reuters on Friday showed global equity funds suffering their largest weekly outflow in nine months, with investors pulling $23.21 billion in the week through September 16 amid oil-price and inflation concerns. U.S. equity funds recorded particularly large withdrawals.
This does not mean a market crash is inevitable. Fund flows can reverse quickly, and investors routinely reposition around major central-bank decisions. But the figures are a useful measure of rising caution.
Why households outside Japan should pay attention
A Japanese interest-rate decision can seem remote to a household in Toronto, London or New York. The connection is indirect, but real.
Japan has long been a major source of relatively cheap capital. When Japanese rates were extremely low, investors could borrow yen cheaply and invest in higher-yielding assets elsewhere — a strategy commonly associated with the so-called yen carry trade. As Japanese rates rise, the economics of those trades can change, potentially affecting currencies, bonds and equities far beyond Japan.
At the same time, the broader global move toward tighter monetary policy matters for ordinary borrowers. In the United States, mortgage rates remain elevated after the Fed’s latest move. Zillow data cited by Yahoo Finance put the average U.S. 30-year fixed mortgage rate at about 7.05% on September 18.
Central banks do not directly set most mortgage rates, and the relationship is not one-for-one. Longer-term bond yields, inflation expectations, economic growth and lender pricing all play a role. Still, a world in which several major central banks are worried about renewed inflation is a very different financial environment from one in which investors expect steady rate cuts.
Japan’s inflation dilemma
The BOJ’s challenge is especially complicated because a weak yen can itself add to inflation. Japan imports much of its energy, so a weaker currency can make oil and other imported goods more expensive in yen terms.
That creates a feedback risk: expensive imports lift prices, the central bank raises rates to restrain inflation, but if markets doubt that rates will rise enough, the yen may remain weak and imported inflation can persist.
The BOJ is not operating in a vacuum. Energy prices, fiscal policy, wages and the decisions of other central banks all influence the outcome. That is why Friday’s 1.25% rate is important, but the path from here is even more important.
What happens next?
The immediate questions are whether the yen stabilizes and how strongly Ueda signals additional tightening. Economists surveyed by Reuters before the meeting expected the BOJ to continue raising rates, with the median view pointing to 1.75% by the second quarter of 2027. Forecasts are not guarantees, and geopolitical or economic shocks could change that path.
Investors will also watch oil prices closely. Sustained high energy costs would make the inflation fight harder for Japan and other energy-importing economies. A meaningful decline in energy prices, by contrast, could reduce some of the pressure on central banks.
For households and investors, the larger message is simpler: the assumption that the next major move in global borrowing costs must be downward no longer looks safe. Japan — once the clearest symbol of permanently cheap money — has now raised rates to a three-decade high. The fact that its currency still fell shows just how complicated the new inflation era has become.
This article is for general information and analysis and does not constitute financial or investment advice.